Equipment Financing for Small Businesses: How It Works and What It Costs
Paying cash for a major piece of equipment feels responsible, no debt, no interest, no lender involved. It is also, in most cases, the most expensive way to acquire it, not in interest paid, but in the working capital it ties up. Equipment financing exists specifically to solve this problem: it lets the equipment pay for itself over time while your cash stays available for payroll, materials, and the operating expenses that keep the business running day to day.
Here is how equipment financing actually works, what it costs, and a real example of how the math plays out.
Equipment Loan vs. Equipment Line of Credit
These are two related but distinct products, and the difference matters depending on how often your business buys equipment.
Equipment loan finances a single purchase. You borrow a set amount, the equipment secures the loan, and you repay it over a fixed term, typically aligned with how long that specific equipment is expected to remain useful.
Equipment line of credit works more like a revolving facility specifically for equipment. Rather than financing one purchase, it gives you ongoing access to capital for equipment needs as they come up, construction companies buying new machinery, transportation businesses expanding a fleet, medical practices upgrading diagnostic equipment. As you pay down the balance, that credit becomes available again for the next purchase, without reapplying from scratch each time.
If your business buys equipment occasionally, a standard equipment loan is simpler. If equipment needs come up repeatedly as the business grows, the line of credit structure saves you from repeating the application process every time.
What Equipment Financing Costs
- Loan amounts: $10,000 to $5 million, depending on business size and equipment value
- Interest rates: 6% to 20% APR, based on creditworthiness and equipment type
- Terms: 24 to 84 months, generally aligned with the equipment’s useful life
- Loan-to-value: 80% to 100% of equipment value can typically be financed
- Funding timeline: 1 to 3 weeks from application to purchase
Credit requirements are more forgiving than most funding products, a 600+ score is generally preferred but not always required, since the equipment itself serves as collateral and reduces the lender’s risk.
Why the Collateral Structure Matters
Because the equipment secures the loan, lenders can offer meaningfully better terms than an unsecured product would carry, lower rates, larger amounts, and more flexible credit requirements. This is the same principle that makes secured lines of credit cheaper than unsecured ones: putting up collateral shifts risk away from the lender, and that gets reflected directly in the price you pay for the capital.
A Real Example: Financing a $200,000 Excavator
Here is how this plays out for an actual business decision.
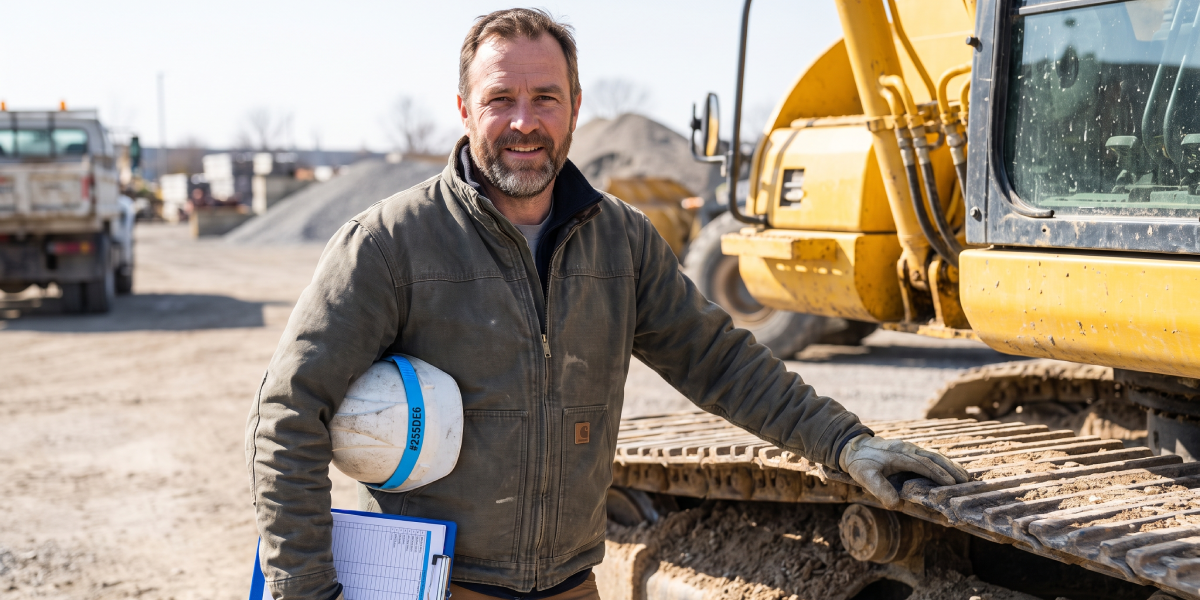
A construction contractor identifies a $200,000 excavator that would unlock larger, more profitable projects. Paying cash would devastate working capital, leaving insufficient funds for payroll, materials, and operating expenses on current projects already underway.
The structure: an equipment line of credit at 80% loan-to-value finances $160,000, with a $40,000 down payment. The equipment itself secures the loan, resulting in a rate around 8% to 12% APR over a 60-month term, roughly $3,500 per month.
The result: $160,000 in working capital stays available for daily operations instead of sitting locked in a single piece of equipment. That $3,500 monthly payment is easily covered by the additional revenue from just one or two extra projects a month, projects the new equipment itself makes possible.
The added benefit: with a line of credit structure specifically, this same facility can be used for future equipment purchases as the balance is paid down, providing ongoing access without a fresh application each time new equipment is needed.
This is the core logic behind equipment financing: the asset generates enough incremental revenue to cover its own payment, while preserving the cash a business actually needs to operate.
Who Equipment Financing Makes the Most Sense For
- Construction companies regularly needing new tools, machinery, or vehicles
- Transportation and logistics businesses maintaining or expanding a fleet
- Medical and dental practices upgrading diagnostic or treatment equipment
- Manufacturers investing in production machinery
- Any business where a piece of equipment directly enables more revenue than its monthly payment costs
The test worth applying before financing any equipment: will this asset generate enough additional revenue or efficiency to comfortably cover its own payment? If yes, financing almost always beats paying cash, since it preserves the working capital that keeps the rest of the business running smoothly.
How to Get Started
- Identify the specific equipment and its cost. Lenders want a clear, itemized picture of what is being financed, not a general request for capital.
- Check your credit and time in business. A 600+ score is generally preferred, though the equipment collateral makes this more flexible than unsecured products.
- Decide between a loan and a line of credit based on whether this is a one-time purchase or an ongoing need.
- Compare lenders. Specialized equipment lenders often understand depreciation schedules and industry-specific equipment values better than general-purpose lenders, which can translate to more favorable terms.
Finance Your Next Equipment Purchase the Right Way
At Lenderly, we match business owners with the equipment financing structure that fits their purchase, credit profile, and how often equipment needs come up, whether that is a single-purchase loan or an ongoing equipment line of credit.
Find your funding match with Lenderly →
Frequently Asked Questions
What credit score do I need for equipment financing? A 600+ score is generally preferred but often not strictly required, since the equipment itself secures the loan and reduces the lender’s risk compared to unsecured financing.
What is the difference between an equipment loan and an equipment line of credit? An equipment loan finances a single purchase with a fixed repayment schedule. An equipment line of credit provides ongoing, revolving access to capital for multiple equipment purchases over time, without needing to reapply for each one.
How much of the equipment cost can be financed? Typically 80% to 100% of the equipment’s value, depending on the lender and the type of equipment being financed.
How long does equipment financing take to fund? Most equipment financing funds within 1 to 3 weeks of application, though this can vary based on the lender and the complexity of the purchase.
Is it better to finance equipment or pay cash? If the equipment will generate enough additional revenue or efficiency to comfortably cover its monthly payment, financing is usually the stronger choice, since it preserves working capital for payroll, materials, and other operating needs rather than tying up cash in a single asset.